If you’re new to business insurance, it can feel confusing.
There are so many types. Different names. Different coverage.
And most business owners ask the same question:
Which types of business insurance do I actually need?
The good news is — it’s simpler than it looks.
In this guide, we’ll break down the main types of business insurance in plain English so you can understand what they do and how they protect your business.
Why understanding insurance types matters
Not all insurance covers the same thing.
If you choose the wrong type, you might think you’re protected — but you’re not.
The right mix of coverage helps you:
- avoid financial loss
- handle problems quickly
- protect your business reputation
- stay professional when issues happen
**
1. General Liability Insurance
This is the most common type.
It covers:
- customer injuries
- property damage
- legal claims
Example:
A customer slips in your store → insurance helps cover medical costs.
👉 Most businesses should start here.
2. Professional Liability Insurance
Also called “errors and omissions” insurance.
It covers:
- mistakes in your work
- service errors
- client disputes
Example:
You give advice that causes a client loss → insurance helps cover the claim.
👉 Important for service-based businesses.
3. Property Insurance
This protects your physical assets.
It covers:
- office space
- equipment
- inventory
Example:
A fire damages your office → insurance helps cover repairs.
Table 1: Core Types of Business Insurance
| Type | What It Covers |
|---|---|
| General Liability | Injuries, damage |
| Professional Liability | Mistakes, errors |
| Property Insurance | Equipment, buildings |
**
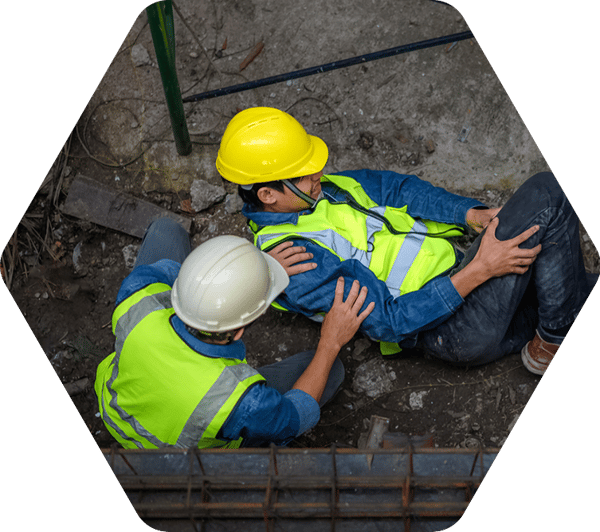
4. Workers’ Compensation Insurance
This covers employees if they get hurt at work.
It includes:
- medical costs
- lost wages
- recovery support
👉 Often required by law if you have employees.
5. Business Interruption Insurance
This helps if your business has to stop operating.
It covers:
- lost income
- temporary closures
- unexpected disruptions
Example:
A flood shuts down your business → insurance helps replace lost income.
6. Cyber Insurance
This protects your business from online risks.
It covers:
- data breaches
- hacking
- cyber attacks
Example:
Customer data is compromised → insurance helps with recovery costs.
👉 Important for online businesses.
7. Business Owner’s Policy (BOP)
This is a bundle.
It combines:
- general liability
- property insurance
👉 It’s often cheaper than buying each separately.
Table 2: Which Insurance You May Need
| Business Type | Recommended Coverage |
|---|---|
| Consultant | Liability + Professional |
| Retail store | Liability + Property |
| Contractor | Liability + Workers’ Comp |
| Online business | Liability + Cyber |
How to choose the right types for your business
You don’t need everything at once.
Start with:
- your biggest risks
- your business type
- your budget
Then build your coverage over time.
How this connects to your reputation
This part matters more than people think.
When something goes wrong:
- customers expect a fast solution
- clients expect professionalism
If you’re covered:
- you can respond quickly
- fix issues smoothly
- protect your business image
If you’re not:
- delays happen
- problems grow
- trust can drop
Being prepared helps you stay reliable and professional.
Real-world examples
Example 1: Service business
Client claims mistake → professional liability covers it
Example 2: Retail store
Customer injury → general liability helps
Example 3: Office business
Equipment damage → property insurance covers costs
Example 4: Online business
Data breach → cyber insurance helps recover
Common mistakes to avoid
- thinking one policy covers everything
- skipping important coverage
- choosing the cheapest option
- not updating policies as you grow
FAQs
1. What are the main types of business insurance?
General liability, professional liability, property, workers’ comp, and cyber insurance.
2. Which insurance is most important?
General liability is usually the starting point.
3. Do I need multiple types of insurance?
Most businesses need more than one type for full protection.
4. What is a BOP policy?
It combines liability and property insurance into one plan.
5. Is cyber insurance necessary?
Yes, especially if you handle customer data online.
6. Can I start with one policy?
Yes, then add more coverage as your business grows.
Conclusion
Understanding the different types of business insurance helps you make smarter decisions.
You don’t need everything right away — but you do need the right coverage.
The right insurance protects your business, your finances, and your reputation.
And when problems happen (because they will), you’ll be ready.
Related Articles
- Do Small Businesses Need Insurance? Here’s the Truth (Simple Guide)
- Why Do Hospitals Have Bad Reviews? 11 Honest Reasons Patients Speak Out
- Comcast Business: 11 Powerful Benefits Every Business Should Know (2026 Guide)
- How Reputation Strategy + Crisis Management Save Brands from Total Meltdown
Latest Articles
-
Google Review Removal Service That Protects Your Reputation and Builds Trust
Can Negative Google Reviews Damage a Healthcare Organization? A sudden wave of negative Google reviews can seriously damage the reputation of a nursing home or medical practice. Families researching nursing homes often compare ratings, recent reviews, management responses, photographs, and overall review activity before scheduling a tour. Patients may perform the same research before choosing…
-
Google Review Management Agency That Helps Businesses Build Trust and Get More Customers
People trust Google reviews before they trust advertisements. Before contacting your business, potential customers usually search your company online and ask themselves one important question: “Can I trust this business?” That answer often comes from your reviews. Customers look at: If your business has weak reviews, outdated feedback, or unanswered complaints, customers may choose a…
-
How to Get New Patients in New York With Google Reviews
Your next patient in New York may decide whether to call your practice before ever speaking to your staff. Today, patients search, compare, and read reviews before choosing care. A 2025 survey found 84% of patients check online reviews before choosing a new healthcare provider. In 2026, 75% said they wouldn’t book with a provider…
-
How Accepted Insurance Plans Can Strengthen Medical Local SEO
When patients search for a doctor, they are not only looking for the right specialty or the closest medical office. Many also need to know whether the practice accepts their insurance. A patient might search Google for: If your website does not clearly list the insurance plans your practice accepts, Google and potential patients may…
-
Brooklyn Nursing Home Marketing in 2026: How to Turn Google Searches Into More Admissions
If you’re responsible for marketing or admissions at a nursing home, you already know how to generate business the traditional way. You know the importance of hospital relationships. You know your discharge planners, case managers, physicians, community partners, and referral sources. You know what happens to census when those relationships are strong, and you know…
-
Google Reviews and Search Console: Drive More Traffic to Your Queens Medical Practice
Google Reviews and Search Console: Drive More Traffic to Your Queens Medical Practice A patient in Queens searches Google for a family doctor, chiropractor, dentist, physical therapist, podiatrist, urgent care center, or medical specialist. Within seconds, that patient may see several practices competing for attention. The listings can look similar, but the patient still has…